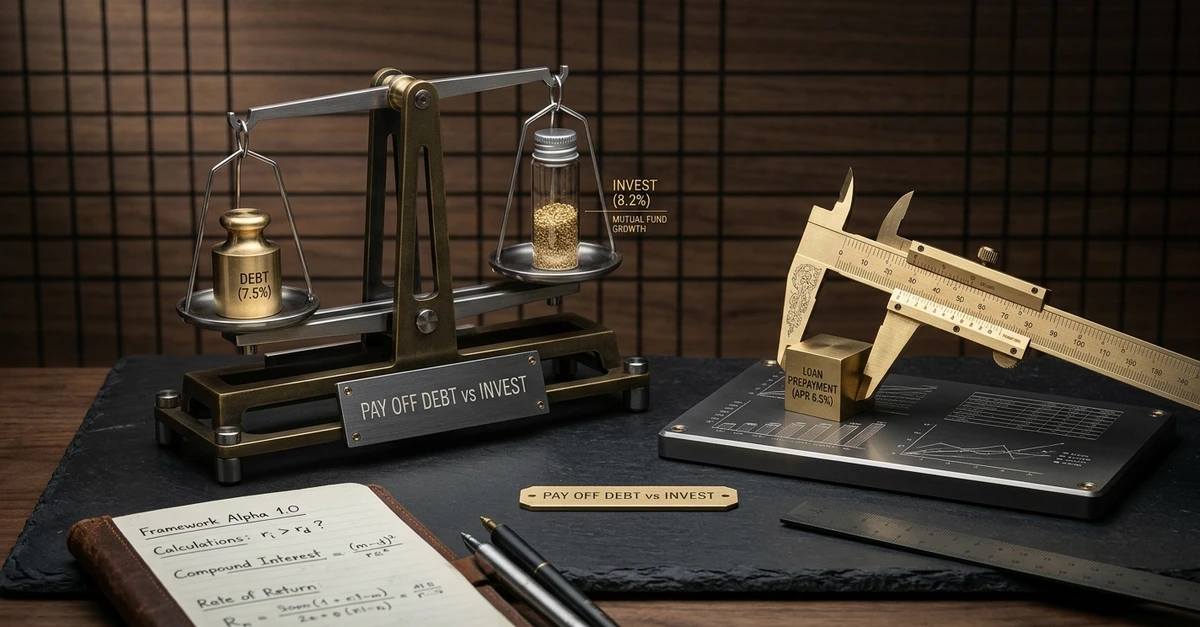

Pay Off Debt vs Invest: A Mathematical Framework for Success
Prepaying high-interest loans isn't just a conservative defensive play—it is a guaranteed, tax-free return on capital.
When evaluating whether to pay off debt vs invest, many professionals fall into a common analytical trap. While equity mutual fund investments offer compelling long-term wealth potential, market performance involves risk. In contrast, prepaying debt delivers immediate downside protection by permanently eliminating future interest obligations. To structure this decision, compare your effective borrowing cost against your expected net investment yield—accounting for any baseline AUM fee or fee-only vs fee-based advisory costs.
For instance, salaried professionals borrowing up to 3 times their annual salary (requiring a minimum net take-home of Rs. 8,000 per month and 3 years continuous employment) must carefully assess debt service ratios. Similarly, self-employed applicants generating net profit after tax over Rs. 1,00,000 per annum for the last 2 years need structured asset allocation rather than taking on uncalculated leverage. If your loan interest rate exceeds expected net mutual fund gains, debt reduction provides a risk-free foundation for future wealth creation.
Balancing systematic loan prepayment with structured investing requires strict financial discipline and experienced guidance. Are you currently prioritizing aggressive debt reduction or expanding your equity portfolio? Let's discuss your framework below.